Micron Rises After Strong Revenue Guidance Offsets Slight Margin Miss
The highly anticipated Micron earnings (since memory is the one place in the sector in the market where all those massive new bond sales are funding) are finally out and they painted a solid, if slightly mixed, picture compared to buyside bogeys.
As we said in our preview, what would matter today is not what the company did in Q4, but how it guided to Fiscal Q1 (ending next calendar quarter), and sure enough Q3 was solid across the board:
- Adjusted EPS $33.42, beating estimates of $31.83
- Adjusted revenue $54.23 billion vs. $11.32 billion y/y, and beating estimates of $51.49 billion
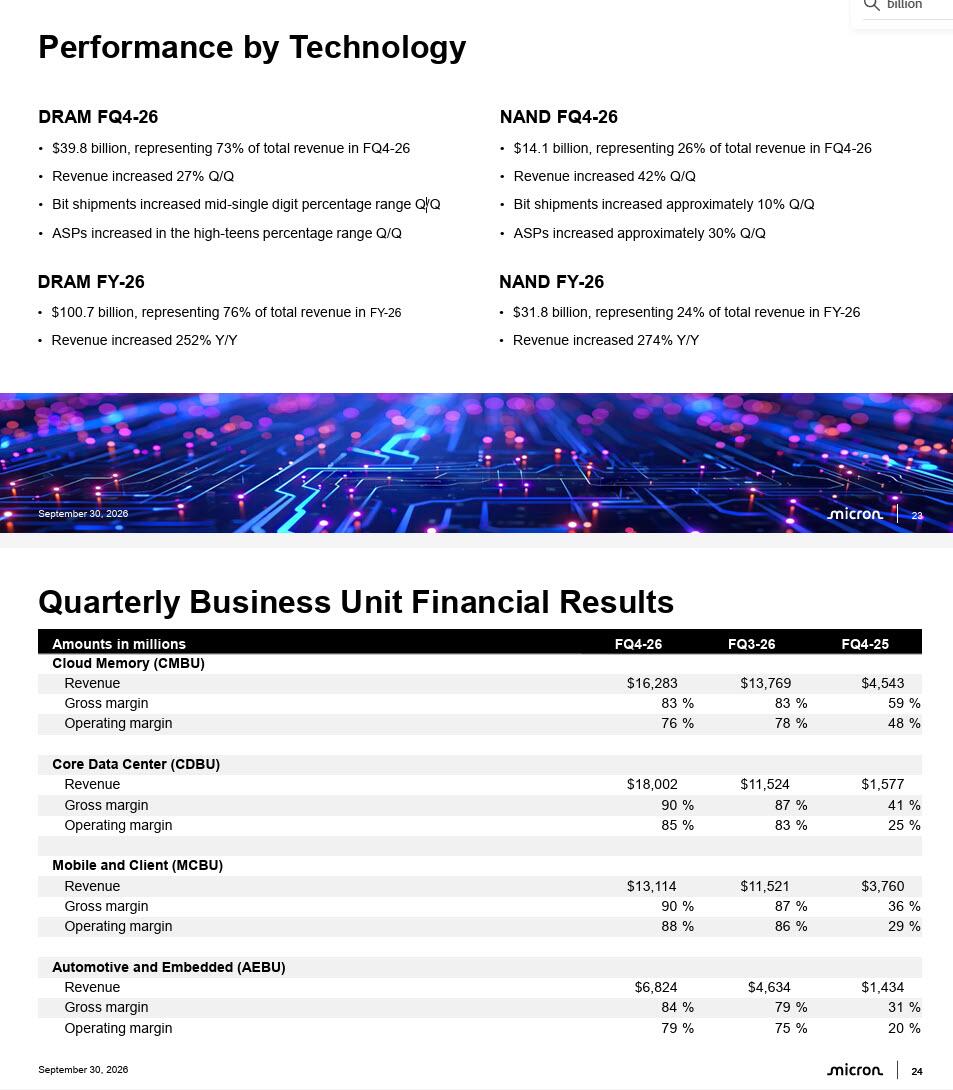
- Core Data Center revenue $18.00 billion, beating estimates of $11.34 billion
- Cloud Memory revenue $16.28 billion, beating estimate $15.14 billion
- Mobile and Client Revenue $13.11 billion vs. $3.76 billion y/y, beating estimates of $12.95 billion
- Automotive and Embedded rev. $6.82 billion, beating estimates of $4.73 billion
- Adjusted gross margin 87% vs. 45.7% y/y, beating estimates of 86.2%
- Adjusted operating income $44.64 billion vs. $3.96 billion y/y, beating estimates of $42.75 billion
- Adjusted operating income margin 82.3% vs. 35% y/y, missing estimates of 82.8%
- Adjusted operating expenses $2.57 billion vs. $1.21 billion y/y, beating estimates of $1.68 billion
- R&D expenses $1.91 billion, +83% y/y, estimate $1.38 billion
- Adjusted operating expenses $2.57 billion vs. $1.21 billion y/y, estimate $1.68 billion
- Cash flow from operations $43.97 billion vs. $5.73 billion y/y, estimate $33.87 billion
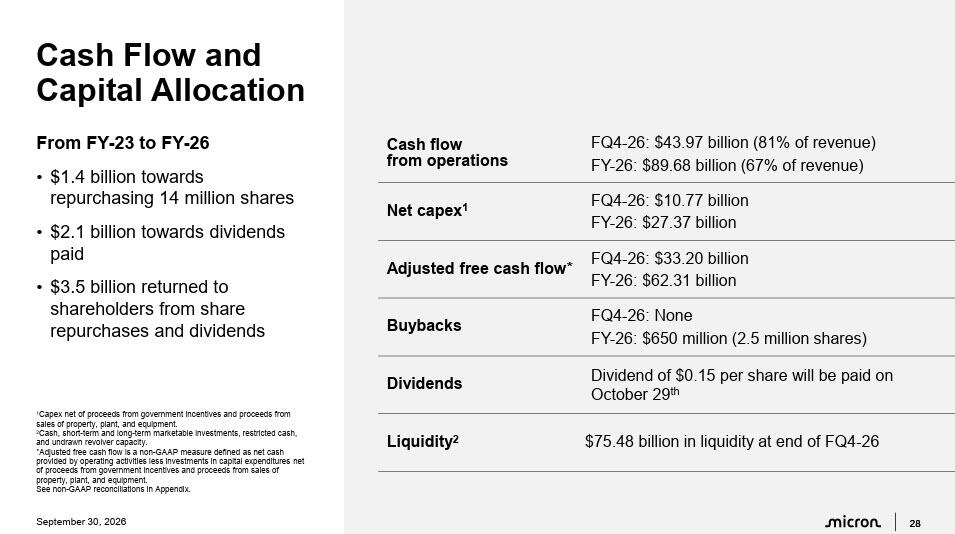
From the slideshow:
“Micron delivered record fiscal 2026 results, and we expect an even stronger fiscal 2027,” CEO Sanjay Mehrotra said in the statement. “Memory enhances this intelligence and the competitiveness of our customers’ platforms.”
So far so good. However, what matters more is guidance and here is why the stock’s after hours reaction has been muted at best:
- Q1 adj. EPS 38.15, beating exp. 35.40.
- Q1 revenue 61.5bln (+/- $1.5BN), beating exp. 57.024bln.
- Q1 gross margin 86.3%, missing exp. 86.7%, and notably below buyside bogeys of 87.5%-88.0%
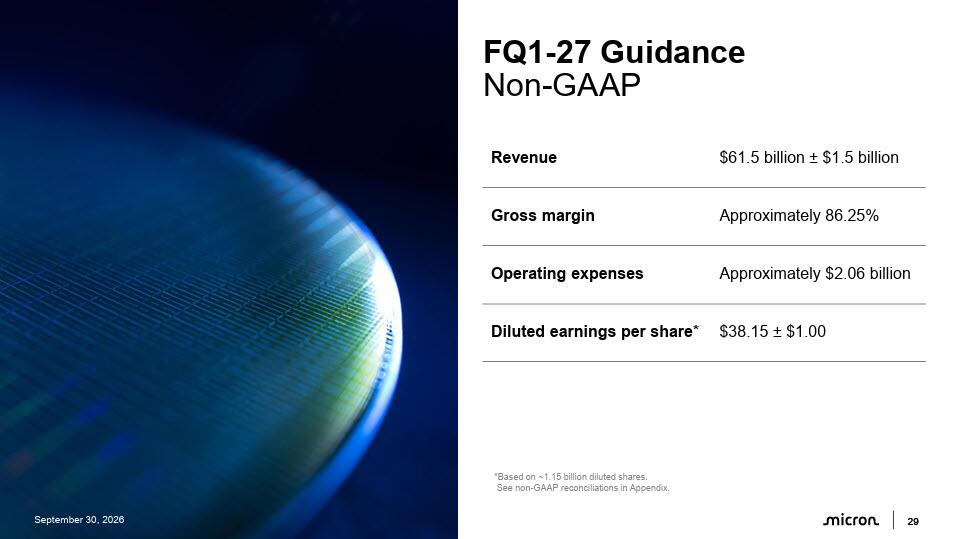
And this is how the company guided:
- We anticipate fiscal Q1 to be the floor for gross margins in fiscal 2027. As Sanjay mentioned, we made a decision to increase fiscal 2026 incentive compensation in fiscal Q4. Most of the increase in fiscal 2026 incentive compensation pertaining to manufacturing was absorbed into inventories in fiscal Q4. As a result, the effects from the sale of these higher cost inventories principally impact fiscal Q1 gross margin. September 30, 2026 September 30, 2026
- Fiscal Q2 benefits from less of this fiscal Q4 related compensation expense, but this benefit is offset by the impact of higher fiscal 2027 incentive compensation. We expect higher gross margins beyond fiscal Q1 for the remainder of fiscal 2027, with a more moderate rate of price increases.
- We project operating expenses to increase by approximately $2.5 billion in fiscal 2027, primarily from higher R&D (research and development) to support an unprecedented set of opportunities in memory and storage and from higher incentive compensation plans.
- We expect a fiscal Q1 and fiscal year 2027 tax rate of around 15.5%
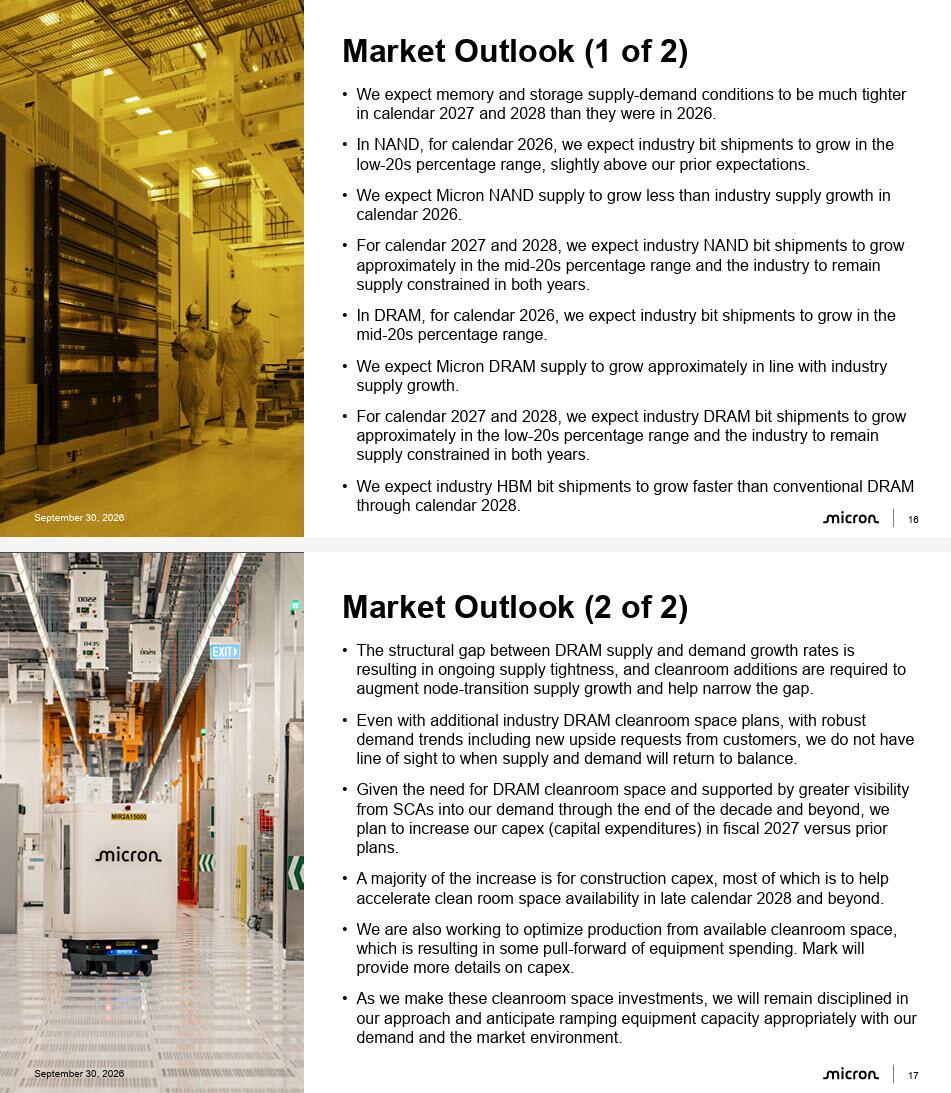
Micron and its rivals continue to be overwhelmed by memory-chip orders. Though the Boise, Idaho-based company is expanding its manufacturing capacity, prices are expected to remain high for the foreseeable future. Here are the highlights from the company’s market outlook:
- Micron (MU) says operating expenses are to increase by about USD 2.5bln in fiscal 2027 and expects memory and storage supply-demand conditions to be much higher in fiscal 2027 and 2028 than in 2026
- In Q1, project capex of around USD 11.5bln and anticipate first-half FY27 capex to be USD 25bln.
- Project CapEx to be higher in H2 FY27.
- Given the need for DRAM cleanroom space and supported by greater visibility from SCAs into our demand through the end of the decade and beyond, we plan to increase our capex (capital expenditures) in fiscal 2027 versus prior plans.
- Expect server unit growth in the high-teens % range in both CY26 and CY27.
- Strong server unit growth is supported by a modestly lower rate of content growth than prior expectations, amid tight memory supply.
“Near-term conditions are still very good, in our view, with strong demand and rising pricing in evidence,” Morgan Stanley analyst Joseph Moore said in a note before the report was released. “The debate has very clearly shifted from, ‘How good can it get?’ to ‘How long can it stay this good?’”
For now the jury is out, as unlike last quarter when the stock blasted off after earnings, this time it is barely moving.
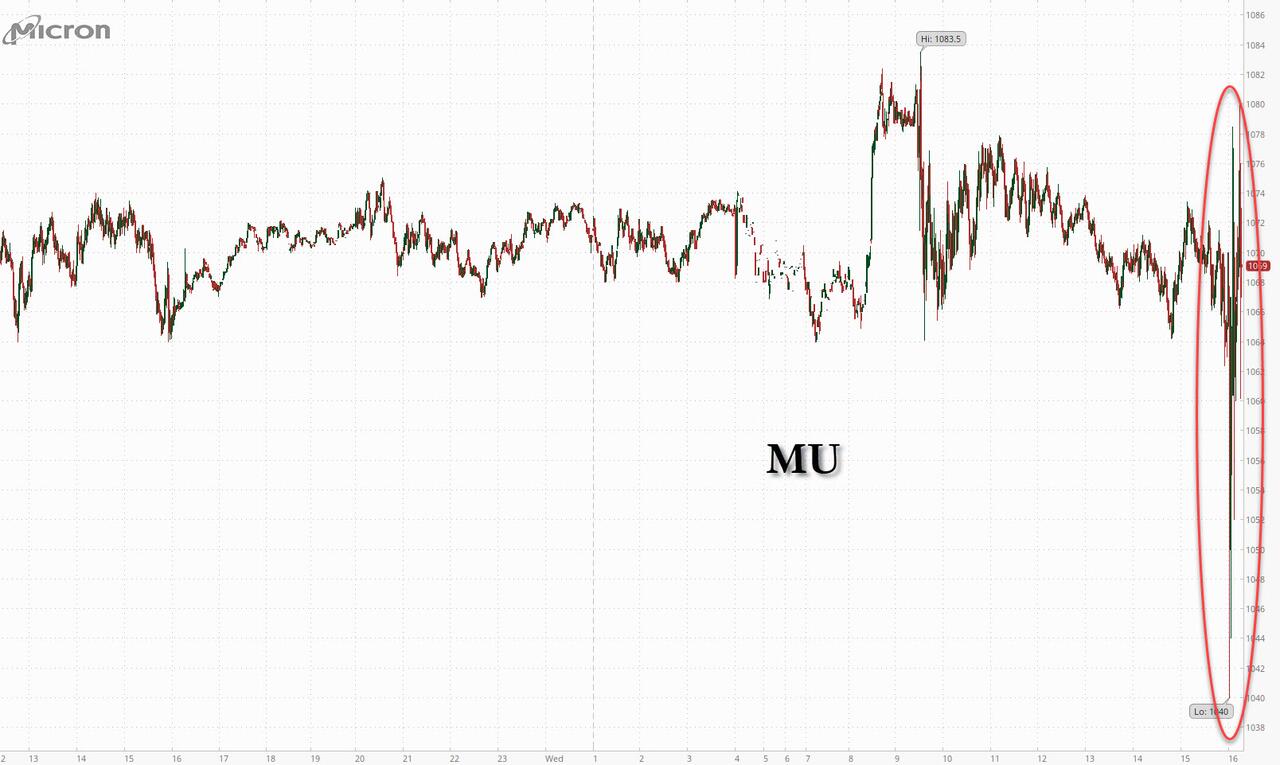
Micron shares were the best performer in the Philadelphia Stock Exchange Semiconductor Index this year, gaining 273%.
Tyler Durden
Wed, 09/30/2026 – 16:28